IBC Amendments: Who Do They Really Serve?
Every successive amendment to the Insolvency and Bankruptcy Code was introduced with the promise of faster resolutions and industrial revival. In practice, each statutory change has systematically tightened the stranglehold of financial creditors, barred first-generation builders from saving their life’s work, and transformed a revival code into a state-backed liquidation machine.
I have watched the Insolvency and Bankruptcy Code evolve since 2016. Every six months, a new amendment. And every time I ask the same question: who do these changes really serve?
Each major IBC change since 2016 strengthened financial creditors and banks — while founder rights and second chances narrowed.
The Bankruptcy Law Reforms Committee designed the Code to save viable businesses. Practice turned it into a recovery tool.
Resolution professionals, valuers, and the insolvency services economy grew — operational creditors and builders often did not.
“The IBC is not an insolvency law. It is a bank recovery law wearing the mask of insolvency reform.”
01Every change strengthens the creditor — the entrepreneur gets nothing
02The IBC Was Supposed to Save Companies. It Became a Recovery Tool for Banks.
I have watched the Insolvency and Bankruptcy Code evolve since 2016. Every six months, there is a new amendment, a new ordinance, a new set of rules. And every single time, I ask myself the same question: who does this change actually help?
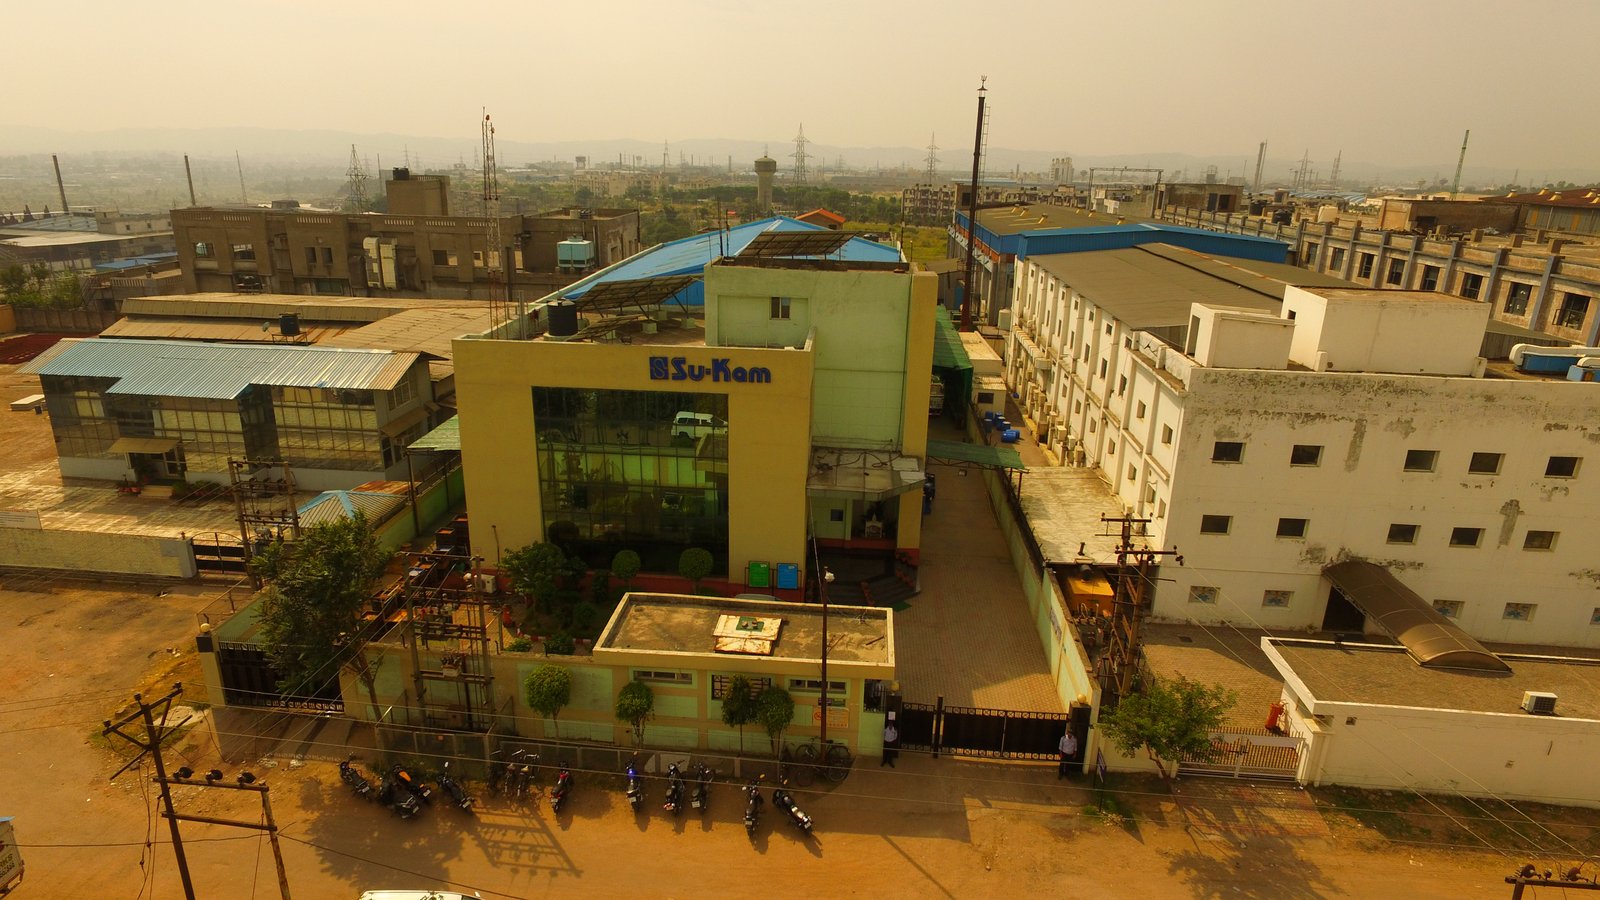
After 35 years of running factories in India and having personally gone through the IBC process with Su-Kam Power Systems, I can tell you the answer. Every major amendment has strengthened the position of financial creditors — the banks. The operational creditors, the employees, and the entrepreneurs have been left behind. Not accidentally. Systematically.
“The IBC is not an insolvency law. It is a bank recovery law wearing the mask of insolvency reform.” — Kunwer Sachdev
03The Original Intention: Rehabilitation and Second Chances
Let us go back to why the IBC was created. The Bankruptcy Law Reforms Committee designed this law with a clear intent: resolve stressed companies quickly, rehabilitate businesses that can be saved, and give entrepreneurs a second chance. The law was supposed to balance the interests of all stakeholders — creditors, employees, operational partners, and the entrepreneur. It was supposed to keep companies alive.
What happened instead is a textbook case of regulatory capture. Every amendment since 2016 has tilted the balance further toward financial creditors — the government-owned banks — while stripping away protections for everyone else.
04The Amendment Timeline: How Every Change Strengthened Creditors
2016 — The IBC is Born
The Code is enacted with noble intentions. Quick resolution, rehabilitation of viable businesses, second chances for entrepreneurs. The Bankruptcy Law Reforms Committee envisioned a balanced system.
2017 — Section 29A: Promoters Barred
This is where the rot begins. The existing promoter is barred from bidding for their own company. Even genuine promoters who fell into stress due to market conditions or banking decisions were permanently excluded. The one person who could unlock maximum value was removed from the race. As legal experts have noted, the restriction resulted in “lenders being devoid of higher prices offered by promoters.”
2018 — COC Gets More Power
The voting threshold for the Committee of Creditors was modified. Section 12A was introduced for withdrawal of applications — but only with 90% COC approval, making it nearly impossible for operational creditors or the company itself to withdraw. The amendments streamlined the process for financial creditors while adding hurdles for everyone else.
2019 — The 330-Day Cap
A deadline of 330 days was imposed for completing CIRP. Sounds good on paper. In practice, it pressured resolution applicants to submit lowball offers and pressured the NCLT to approve whatever was on the table. The real beneficiary? Financial creditors who wanted quick disposal, not rehabilitation. A provision was added that operational creditors should receive at least the liquidation value — but when the liquidation value itself is near zero because the company has been bled dry during an extended CIRP, what is that guarantee worth?
2020 — COVID Suspension
The government suspended fresh IBC filings for defaults arising during COVID. This protected companies temporarily. But it did nothing to address the cases already in the pipeline — companies that were dying while the courts were closed.
2026 — The Latest Overhaul (CIIRP)
The IBC Amendment Act 2026, which received Presidential assent on April 6, 2026, is the most comprehensive change since the Code’s enactment. And once again, the primary beneficiaries are financial creditors. The new Creditor-Initiated Insolvency Resolution Process (CIIRP) allows financial creditors holding just 51% of debt to directly trigger insolvency proceedings with compressed 150-day timelines.
05What the 2026 Amendment Actually Does
Mandatory admission of petitions when default is proved — removing judicial discretion that sometimes protected companies.
Expansion of the look-back period for avoidance transactions to two years — giving creditors more ammunition.
Removal of fast-track insolvency for small firms — eliminating the one pathway designed for MSMEs.
Evidentiary sufficiency of information utility records under Section 7 — making it easier for financial creditors to file and harder for debtors to contest.
Benefits: Creditors. Every single provision above strengthens the financial creditor’s position.
06The Waterfall That Drowns Operational Creditors
Section 53 of the IBC defines the priority of payments in liquidation — the so-called “waterfall mechanism.” The order tells you everything about whose interests this law protects:
1. CIRP and liquidation costs (lawyers, RPs, Big Four firms get paid first)
2. Workmen’s dues (only 24 months)
3. Secured financial creditors
4. Employee dues (only 12 months)
5. Unsecured financial creditors
6. Operational creditors — HERE, at number six
7. Government dues
8. Equity shareholders
Operational creditors — the suppliers who provided raw materials on credit, the service providers who kept the factory running, the small businesses whose survival depends on being paid — are ranked below every category of financial creditor. In practice, by the time the waterfall reaches operational creditors, there is nothing left.
The Recovery Gap:
Financial creditors recovered 37% of their claims in 2024-25.
Operational creditors recovered just 10%.
That is not a gap — that is a chasm.
07Did Banks Invest to Keep Companies Alive? The Answer Is No.
Here is the real scandal that no amendment addresses. When a company enters CIRP, it needs working capital to stay alive. Orders need to be fulfilled. Salaries need to be paid. Raw materials need to be purchased. Without working capital, the company’s value erodes every single day.
The financial creditors — the banks who filed the IBC application, who sit on the COC, who control the process — rarely invest a single rupee to keep the company running during CIRP. They drag the company into insolvency, watch its value bleed out over 744 days (the current average CIRP duration as of March 2026, more than double the mandated 330 days), and then express shock when the recovery is poor.
IBC at a Glance — March 2026
8,987 cases admitted | 1,419 resolved (15.8%) | 3,003 liquidated (33.4%) | 744 days average CIRP duration
More than two companies are liquidated for every one that is saved. And the ones that were liquidated — how many could have survived if the COC had invested to keep them running? Nobody tracks this number. Because the answer would expose the fundamental hypocrisy: the creditors who demand maximum recovery are the same ones who refuse to invest in preserving the asset.
08What the IBC Amendments Should Have Done — But Did Not
Reform 1: Mandatory working capital funding during CIRP. If you file for IBC, you should be required to fund the company’s operations during the process.
Reform 2: Operational creditor representation on COC with real voting rights, not tokenism.
Reform 3: Time-bound accountability for the COC. If their decisions lead to value destruction, there should be consequences.
Reform 4: A separate MSME framework — small companies cannot survive the cost and duration of full CIRP.
Reform 5: Amend Section 29A to allow genuine promoters. The promoter knows the business better than any vulture fund.
Reform 6: Measure recovery against company valuation at start of CIRP, not against inflated claim amounts.
09The Insolvency Industry: Who Really Benefits?
If creditors are recovering less, companies are being liquidated, and operational creditors are getting almost nothing — who is actually benefiting? The answer: the insolvency industry itself. The Resolution Professionals who manage multiple companies simultaneously with no accountability. The Big Four accounting firms and corporate law firms that charge crores in fees — fees that come out of the company’s remaining value. In Su-Kam’s case alone, ₹40 crores was consumed in CIRP costs in one year.
The IBC has created a thriving ecosystem of professionals who profit from corporate distress. Every amendment that extends timelines, adds complexity, or creates new procedural requirements feeds this ecosystem. And this ecosystem has no incentive to fix the problems — because the problems are their business model.
10The Way Forward
India needs its IBC to work. A functioning insolvency framework is essential for economic confidence, credit markets, and entrepreneurship. But working does not mean working for one stakeholder at the expense of all others.
The next round of IBC amendments must address the structural imbalance. Operational creditors need real representation, not tokenism. Entrepreneurs need a fair exit, not criminal prosecution. MSMEs need a separate pathway, not the same expensive process designed for large corporates. And most importantly, the creditors who control the process must be held accountable for the outcomes they produce.
Until then, every amendment will follow the same pattern: more power to creditors, more process for professionals, and more destruction for the entrepreneurs who built these companies.
Kunwer Sachdev is the founder of Su-Kam Power Systems He has over 35 years of experience in Indian manufacturing. This is Part 1 of “The IBC Files” — a series examining India’s insolvency framework from an entrepreneur’s perspective.
We bid with a Kotak Bank term sheet of ₹250 crore. The bid was rejected. After three years that destroyed the organisation, they recovered ₹8 crore — and the Su-Kam brand was sold at zero value during COVID.
11In this series
Eleven linked essays from CIRP and liquidation, written by a founder who lived them. Series hub: The IBC Files.
- Article 1: IBC Amendments: Who Do They Really Serve? (this article)
- Article 2: How IBC, Banks & Bureaucracy Destroy Manufacturing Entrepreneurs
- Article 3: IBC: A Debt Trap for Entrepreneurs — My Personal Ordeal
- Article 4: Fair Value vs Liquidation Value Under the IBC
- Article 5: Section 29A — The Law That Bars Promoters from Bidding
- Article 6: Inside the CIRP — 180 Days of Founder Helplessness
- Article 7: What Happens in NCLT Liquidation: The Su-Kam Case
- Article 8: The Entrepreneur as Criminal — Human Cost of the IBC
- Article 9: Personal Insolvency — The Last Straw
- Article 10: IBBI Penalised the RP & Liquidator — No Compensation for the Entrepreneur
- Article 11: The Silent Bloodbath — How IBC Wipes Out Operational Creditors
Founder of Su-Kam and Kunwwer.ai — the “Inverter Man of India” and the “Solar Man of India.” Read his story →