THE IBC FILES · ESSAY 04
Fair Value vs Liquidation Value Under the IBC
The IBC was sold to India on the promise of transparent economic benchmarks: Fair Value and Liquidation Value. In practice, these figures are calculated secretly behind closed doors without founder input, discounting brand equity and technology patents to zero—turning a ₹300-crore enterprise into a ₹9-crore fire sale while personal guarantees are weaponized to absorb the destruction.
Part of The IBC Files — Read the 11-essay policy playbook.
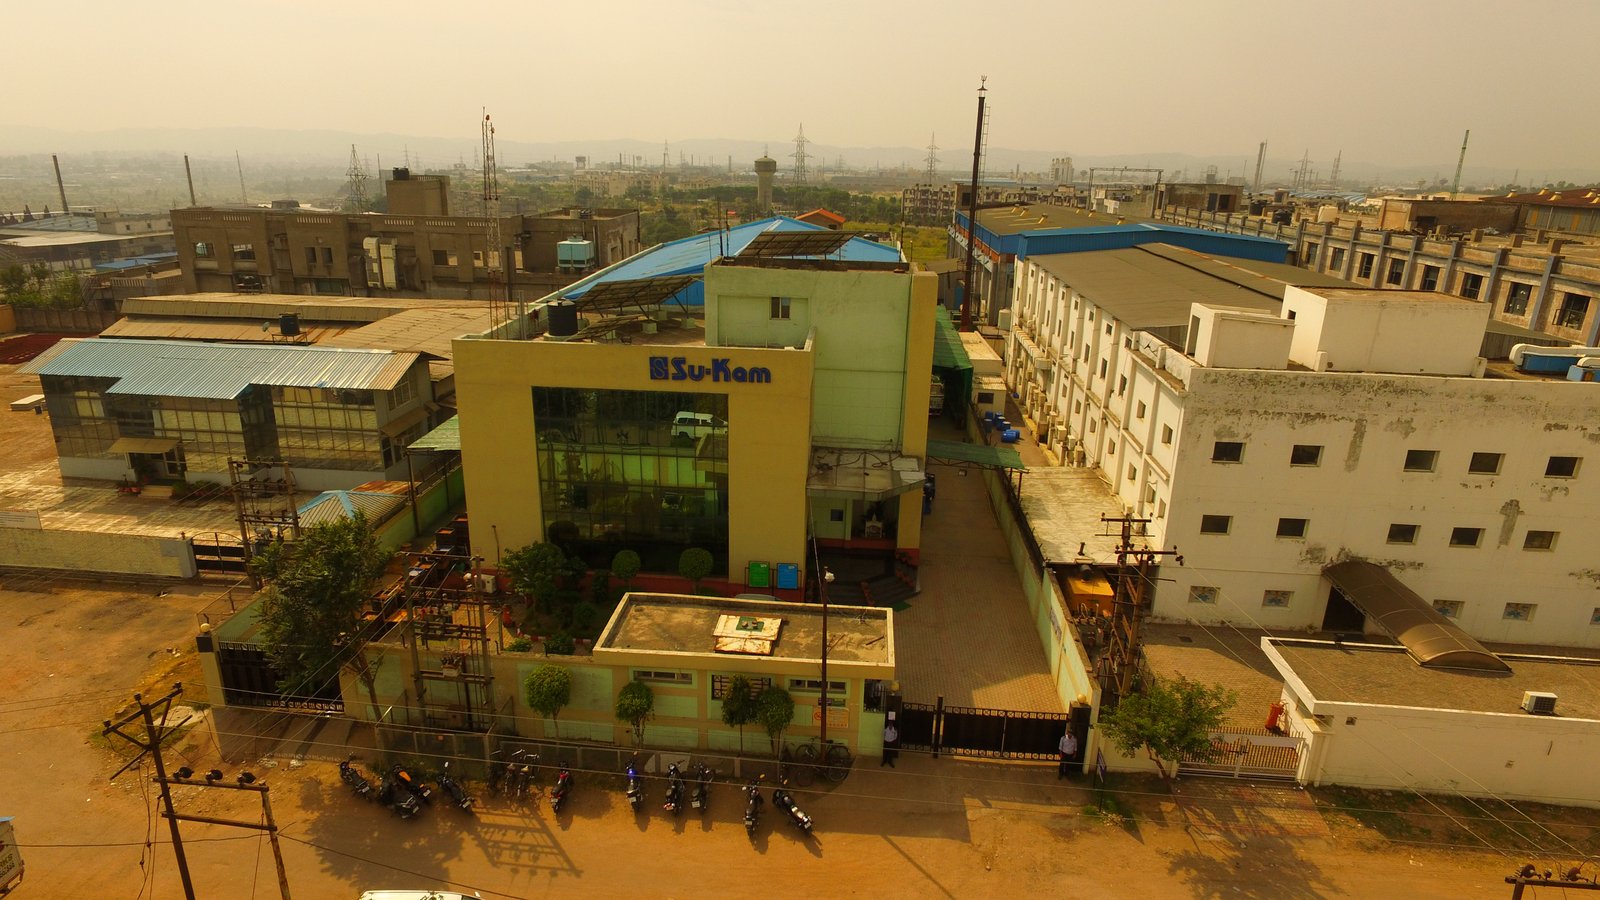
The IBC was sold as a transparent process anchored by Fair Value and Liquidation Value. In practice, I watched a ~₹300 crore going concern get hollowed out under the CoC’s watch and sold for a pittance — while our Kotak-backed ₹250 crore bid was rejected — and after three years of organisational destruction, recovery was ₹8 crore with the Su-Kam brand sold at zero value in COVID.
A running going-concern can only have a Fair Value; assigning liquidation scrap value assumes death before attempting a cure.
Publishing a liquidation floor invites vulture funds to bid at scrap rates rather than enterprise worth.
When a ₹1,000-crore company with a ₹300-crore valuation is sold for ₹5 to ₹10 crore, valuation reports are meaningless bureaucratic theater used to justify 95%+ bank haircuts.
“If a company is operating as a going concern, it can only have a Fair Value. Assigning a ‘Liquidation Value’ to a living factory is an admission that the system wants to scrap it. And when a ₹1,000-crore enterprise with a ₹300-crore valuation is sold for ₹5 crore, what was the point of the valuation at all?”
The IBC was sold to us as a transparent process anchored by two valuations — Fair Value and Liquidation Value. In theory, these numbers are the pillars that keep creditors honest and give the resolution applicants something real to bid against. In practice, I watched my own company — valued at around ₹300 crore — get hollowed out under the CoC’s watch and sold for a pittance. This is what the two valuations are supposed to do, and what actually happens.
For founders seeking AI legal diagnostics and dispute risk assessment, explore Legal Shield on https://kunwwer.ai/.
01Fair Value vs Liquidation Value — What I Saw Happen to Su-Kam
⚖ The Two Valuations the IBC Promises
At the start of every CIRP, the code mandates two valuations of the corporate debtor. They are not paperwork. They are meant to be the spine of the entire process.
The honest market appraisal of the company as a going concern. For creditors, it is the benchmark to judge whether a resolution plan is worth accepting. For resolution applicants, it is the number that lets them build a real bid.
The price the assets would fetch if the company were broken up and sold piece by piece. It is the floor below which no resolution plan should ever be accepted.
Used together, these two numbers are supposed to stop two specific abuses: undervaluation (assets stolen at distressed prices) and overvaluation (bids that look good on paper but never close). They are meant to keep the entire room accountable.
⚠ The Fatal Contradiction: Why Assign Scrap Value to a Living Company?
The IBC states its primary mandate is the revival of a corporate debtor as a “going concern.” If an enterprise is operating, manufacturing, and employing thousands of workers, it can only legitimately have a Fair Value. What is the real intention behind calculating a “Liquidation Value” at the very start of CIRP? It presupposes failure from day one, anchoring the minds of lenders and vulture bidders to scrap worth.
Worse, these elaborate valuation reports become a complete farce at the finish line. What is the economic utility of spending crores on Big-4 valuation reports—debating whether the Fair Value is ₹300 crore or the Liquidation Value is ₹100 crore—if a ₹1,000-crore enterprise is ultimately handed over for ₹5 to ₹10 crore? If a company worth hundreds of crores is sold for pennies, valuation reports do not protect the business, the banks, or the suppliers—they only serve as bureaucratic paperwork to justify a 95%+ haircut.
🚫 The Catch: I Was Never Asked
Here is the design flaw that breaks the whole system: the valuation is done without the promoter’s input. The person who built the company, who knows what every asset is actually worth, who can tell you which contract is live and which customer is loyal — that person is treated as if he were not in the room. And then, under Section 29A, he is barred from even bidding on his own company.
So the chain becomes: lose the company, lose the right to buy it back, lose the personal assets to the personal guarantee, and lose the public’s understanding of what really happened. The very person responsible for creating the value being sold gets no say in how that value is calculated, defended, or realised. I broke down the full debt-trap mechanics in IBC: A Debt Trap for Entrepreneurs — My Personal Ordeal.
“Was it the legislature’s intent that a life’s work could be ruined and the promoter’s integrity questioned — with the promoter denied a voice?”
📊 What ₹300 Crore Became: The Su-Kam Timeline
I am going to tell you exactly what happened to Su-Kam, in numbers, because the numbers tell the story better than I can.
- April 2018: Su-Kam, a ₹600 crore-revenue brand with a market presence and a functioning workforce, was taken into CIRP under the IBC.
- Fair valuation assessed at around ₹300 crore. That number, by the code’s own design, was the benchmark every subsequent decision was supposed to honour.
- Under the RP and the CoC, the company was allowed to decay. More debt was accumulated. Operational value was systematically stripped. (See The Day Su-Kam Died for the day the music stopped.)
- We bid with a Kotak Bank term sheet of ₹250 crore; the bid was rejected. After three years that destroyed the organisation, banks recovered ₹8 crore and the Su-Kam brand was sold at zero value during COVID.
- The company was sold during COVID at a fraction of its worth. The banks — the same banks the code was supposed to protect — received just ₹8 crore. The rest? Recovered by invoking my personal guarantee.
💔 The Human Bill Nobody Adds Up
The financial numbers are damning enough. The human bill is heavier. Thousands of Su-Kam employees lost their jobs. Suppliers who had built their businesses around us went bankrupt. Customers who had trusted the brand for years were left without service support. The brand, the properties, the intellectual property — the entire legacy — was acquired by someone else for a pittance.
And the founder? I was labelled a wilful defaulter in public, called by angry customers and dealers who had no way of knowing what had actually happened inside that boardroom, and dragged through personal insolvency proceedings. The criminalisation angle — how business failure quietly gets treated like a crime — I broke down in The Entrepreneur as Criminal: When Business Failure Becomes a Death Sentence in India.
🔨 What an Honest Valuation Regime Would Look Like
If the IBC is going to be salvaged, the two valuations must stop being decoration and start being the spine of the process. Here is what has to change:
- Make Fair Value binding. No resolution plan should be approved below Fair Value without a hard, recorded justification — and certainly not without notice to the promoter.
- Make Liquidation Value the floor — absolutely. If a deal closes below it, every party that voted for that deal answers for it.
- Give the promoter a structured right to be heard on valuation. Not a veto, a voice. The person who built the company has data the valuer needs.
- Stop the interest clock when CIRP begins. Compounding interest while the company is being deliberately starved is mathematically dishonest. I argued this further in IBC Amendments: Who Do They Really Serve?
- Re-open Section 29A. Honest promoters who can bring a competitive bid should be allowed to compete, with safeguards against fraud — not blanket-banned.
- Hold the CoC to a code of conduct. Without enforceable conduct rules, every valuation in this code is just a number waiting to be ignored.
💭 What I Want the Next Generation of Entrepreneurs to Know
The current IBC framework, in the way it actually operates, is telling every founder in India: build a business, take risks, employ thousands — and if anything goes wrong, you will lose the company, your personal wealth, your reputation, and your voice, in that order. That is not a bankruptcy code. That is a deterrent against entrepreneurship.
Su-Kam’s story is not just my story. It is a warning. If we want the next generation to keep building, we have to fix the system that destroyed the last one — and the two valuations are exactly where that fix has to start.
FAQFrequently Asked Questions
What is fair value vs liquidation value under the IBC?
Fair value estimates a going-concern or market-based worth; liquidation value estimates forced-sale proceeds. Under IBC, these numbers heavily shape bids, recoveries, and what a founder can still lose personally.
Why do valuation gaps matter to founders?
If assets are valued low for process purposes but personal liabilities remain high, the entrepreneur can be forced into distressed sales and residual personal claims that outlast the company.
Who controls valuation in CIRP/liquidation?
Valuers are appointed within the IBC process; Kunwer Sachdev argues founders have little real say, while timelines and incentives can favor mechanical or lender-friendly estimates over enterprise reality.
How can valuation reform help entrepreneurs?
Transparent methods, contestability, and alignment between what is demanded personally and what the process actually realizes from assets.
••In this series
Eleven linked essays from CIRP and liquidation, written by a founder who lived them. Series hub: The IBC Files.
- Article 1: IBC Amendments: Who Do They Really Serve?
- Article 2: How IBC, Banks & Bureaucracy Destroy Manufacturing Entrepreneurs
- Article 3: IBC: A Debt Trap for Entrepreneurs — My Personal Ordeal
- Article 4: Fair Value vs Liquidation Value Under the IBC (this article)
- Article 5: Section 29A — The Law That Bars Promoters from Bidding
- Article 6: Inside the CIRP — 180 Days of Founder Helplessness
- Article 7: What Happens in NCLT Liquidation: The Su-Kam Case
- Article 8: The Entrepreneur as Criminal — Human Cost of the IBC
- Article 9: Personal Insolvency — The Last Straw
- Article 10: IBBI Penalised the RP & Liquidator — No Compensation for the Entrepreneur
- Article 11: The Silent Bloodbath — How IBC Wipes Out Operational Creditors
Founder of Su-Kam and Kunwwer.ai — the “Inverter Man of India” and the “Solar Man of India.” Read his story →