IBC: A Debt Trap for Entrepreneurs — My Personal Ordeal
How a ₹500-crore manufacturing powerhouse with 70+ patents was driven into an inescapable debt spiral. When banks freeze working capital lines during cyclical downturns, the IBC does not rehabilitate—it suffocates the enterprise, bars the founder from rescue under Section 29A, and converts operational distress into personal ruin.
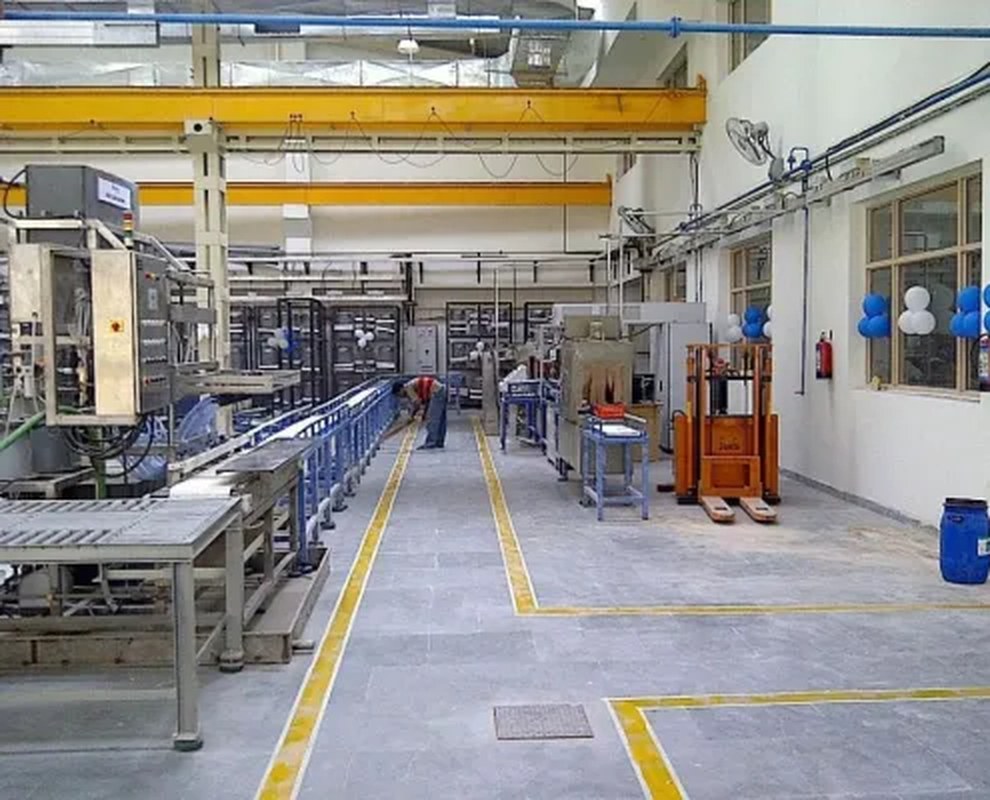
When an Indian company enters insolvency, the Code does not only restructure a balance sheet. It can trap the builder — livelihood, reputation, and decades of work — long after the factory is gone.
How promoters remain permanently chained to corporate debt even after the company is liquidated.
Banks write off bad loans on balance sheets, while the entrepreneur loses livelihood, reputation, and life’s work.
Why genuine risk-taking in Indian manufacturing is treated with punitive suspicion instead of structured second chances.
“When an Indian company enters insolvency, the law doesn’t just resolve the balance sheet—it traps the builder, discounting decades of genuine innovation.”
IBC, IBC: A Debt Trap for Entrepreneurs — My Personal Ordeal — THE IBC FILES: AN ENTREPRENEUR’S PERSPECTIVE
01How the Code becomes a trap for honest founders
← Previous: Article 2 — The Broken System
02The IBC Debt Trap for Entrepreneurs — My Personal Ordeal and a Call for Reform
⚖What the Delhi High Court’s Judgment in My Case Just Exposed
The IBC debt trap is not an abstract idea for me — I have lived it. The recent Delhi High Court verdict in Kunwer Sachdev vs. IDBI Bank and Ors. is, in my view, a turning point. The court did not flinch from naming what every entrepreneur who has gone through this process already knows: the Committee of Creditors operates without a code of conduct, and the entire IBC machinery quietly tolerates it.
The judgment crystallised three things I had been saying for years:
- There are no clear guidelines for the COC. The body that effectively decides whether a company lives or dies has no enforceable rules governing how it behaves. That vacuum is where arbitrary action and zero accountability live.
- Company value erodes inside CIRP itself. The court recognised what insiders have known forever — the process designed to preserve value often destroys it, through COC action or inaction.
- The IBBI must now formulate a code of conduct for COCs. The court directed it. This is the first time the regulator has been told, in writing, to bring transparency and accountability into a process that has had neither.
Read the full coverage of the judgment →
📊The Valuation Paradox I Watched Drain My Company
One of the cruelest design flaws in the IBC is the valuation process. The code mandates two valuations — fair value and liquidation value — at the very start of insolvency. I watched those valuations get done. I also watched them become completely irrelevant to what happened next.
The company is eventually sold or liquidated based on entirely different factors. The valuations end up as an expensive, time-consuming formality that drains money from a company that needs every rupee to survive. The original intent was sound: prevent the COC from eroding the asset, and give the entrepreneur a fair exit number. The code, as written, operationalises neither.
💔The Human Cost I Have Seen With My Own Eyes
Without a valuation-based benchmark, the entrepreneur ends up carrying the full weight of the debt — regardless of what the company is actually worth. Add to that the aggressive tactics creditors routinely use, and you have a recipe for mental collapse. I am not speaking from a study. I have lived it. And I know entrepreneurs who did not survive it.
When you strip a person of his company, his dignity, his standing — and then keep adding interest on a debt the company can never repay — you are not running a bankruptcy code. You are running a slow execution.
🔨What a Real Overhaul Looks Like — My Demand
The IBC, as it stands today, is not a recovery mechanism. It is a tool of oppression for the entrepreneur and a slow drain on the lenders too. If we are serious about salvaging its original purpose, here is what has to change:
- Make valuation binding. Fair value and liquidation value must determine the ceiling of recoverable debt, not sit in a file as decoration.
- Stop the interest clock the day CIRP begins. Continuing to compound interest on an admitted-stressed asset is mathematically dishonest.
- Bind forensic audits, fraud probes, and defaulter declarations to the valuation. No more open-ended harassment.
- Enforce a COC code of conduct — with teeth. The court has now directed IBBI to draft it. It must be enforceable, not advisory.
- Give the entrepreneur a real chance at redemption. A dignified exit is not a favour; it is the cornerstone of any honest bankruptcy regime.
💭Why I Am Speaking About This Publicly
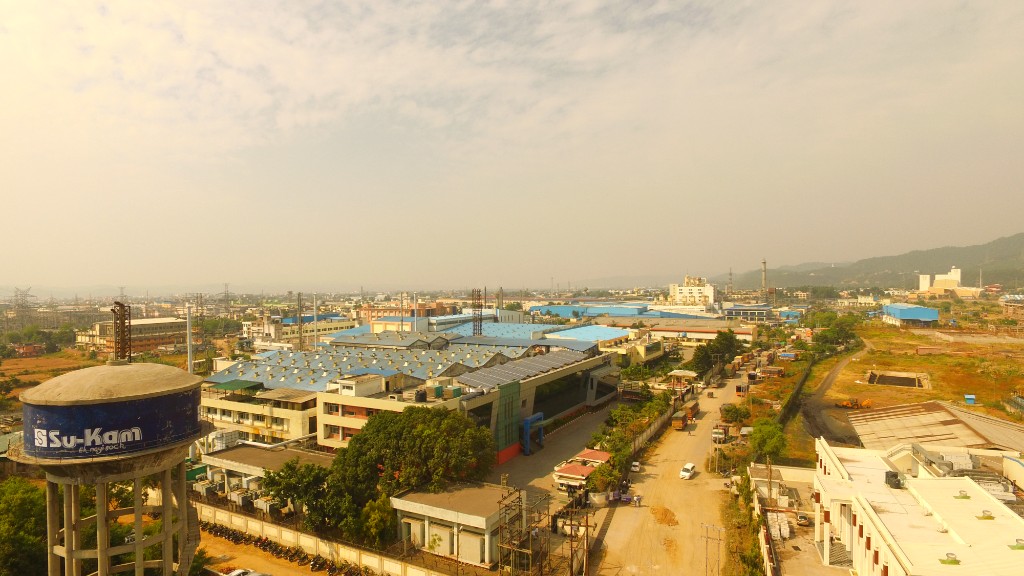
I am speaking because the cost of staying silent has been paid by too many entrepreneurs already. I built Su-Kam for thirty years. I watched the IBC dismantle it in ways that had little to do with the company’s actual condition and everything to do with how the process is structured. If my judgment, my hearing, and my voice can push the system one inch closer to fairness, then this article has done its job.
We bid with a Kotak Bank term sheet of ₹250 crore. The bid was rejected. After three years that destroyed the organisation, they recovered ₹8 crore — and the Su-Kam brand was sold at zero value during COVID.
FAQFrequently Asked Questions
Why does Kunwer Sachdev call the IBC a debt trap?
He describes how default, personal guarantees, compounding interest, and multi-forum cases can trap a founder long after the business is gone—turning commercial failure into lifelong liability.
What personal ordeal does this essay cover?
It recounts his Su-Kam-related experience as a call for reform: how process design and creditor incentives can deepen distress instead of resolving it.
Does settling bank dues end the entrepreneur’s ordeal?
Often not. Parallel DRT, wilful-defaulter, fraud tags, and criminal proceedings can continue even after commercial settlement discussions.
What reform is he calling for?
A genuine fresh-start framework: time limits, separation of honest failure from fraud, and closure that actually releases a founder to rebuild.
••In this series
Eleven linked essays from CIRP and liquidation, written by a founder who lived them. Series hub: The IBC Files.
- Article 1: IBC Amendments: Who Do They Really Serve?
- Article 2: How IBC, Banks & Bureaucracy Destroy Manufacturing Entrepreneurs
- Article 3: IBC: A Debt Trap for Entrepreneurs — My Personal Ordeal (this article)
- Article 4: Fair Value vs Liquidation Value Under the IBC
- Article 5: Section 29A — The Law That Bars Promoters from Bidding
- Article 6: Inside the CIRP — 180 Days of Founder Helplessness
- Article 7: What Happens in NCLT Liquidation: The Su-Kam Case
- Article 8: The Entrepreneur as Criminal — Human Cost of the IBC
- Article 9: Personal Insolvency — The Last Straw
- Article 10: IBBI Penalised the RP & Liquidator — No Compensation for the Entrepreneur
- Article 11: The Silent Bloodbath — How IBC Wipes Out Operational Creditors
Founder of Su-Kam and Kunwwer.ai — the “Inverter Man of India” and the “Solar Man of India.” Read his story →