How Startup India hype and IBC wrecked Indian manufacturing
The Manufacturing Mirage: Four Essays on IBC, Hardware, and Reform
India sold two clocks as rescue. Both kill plants.
The Two Clocks
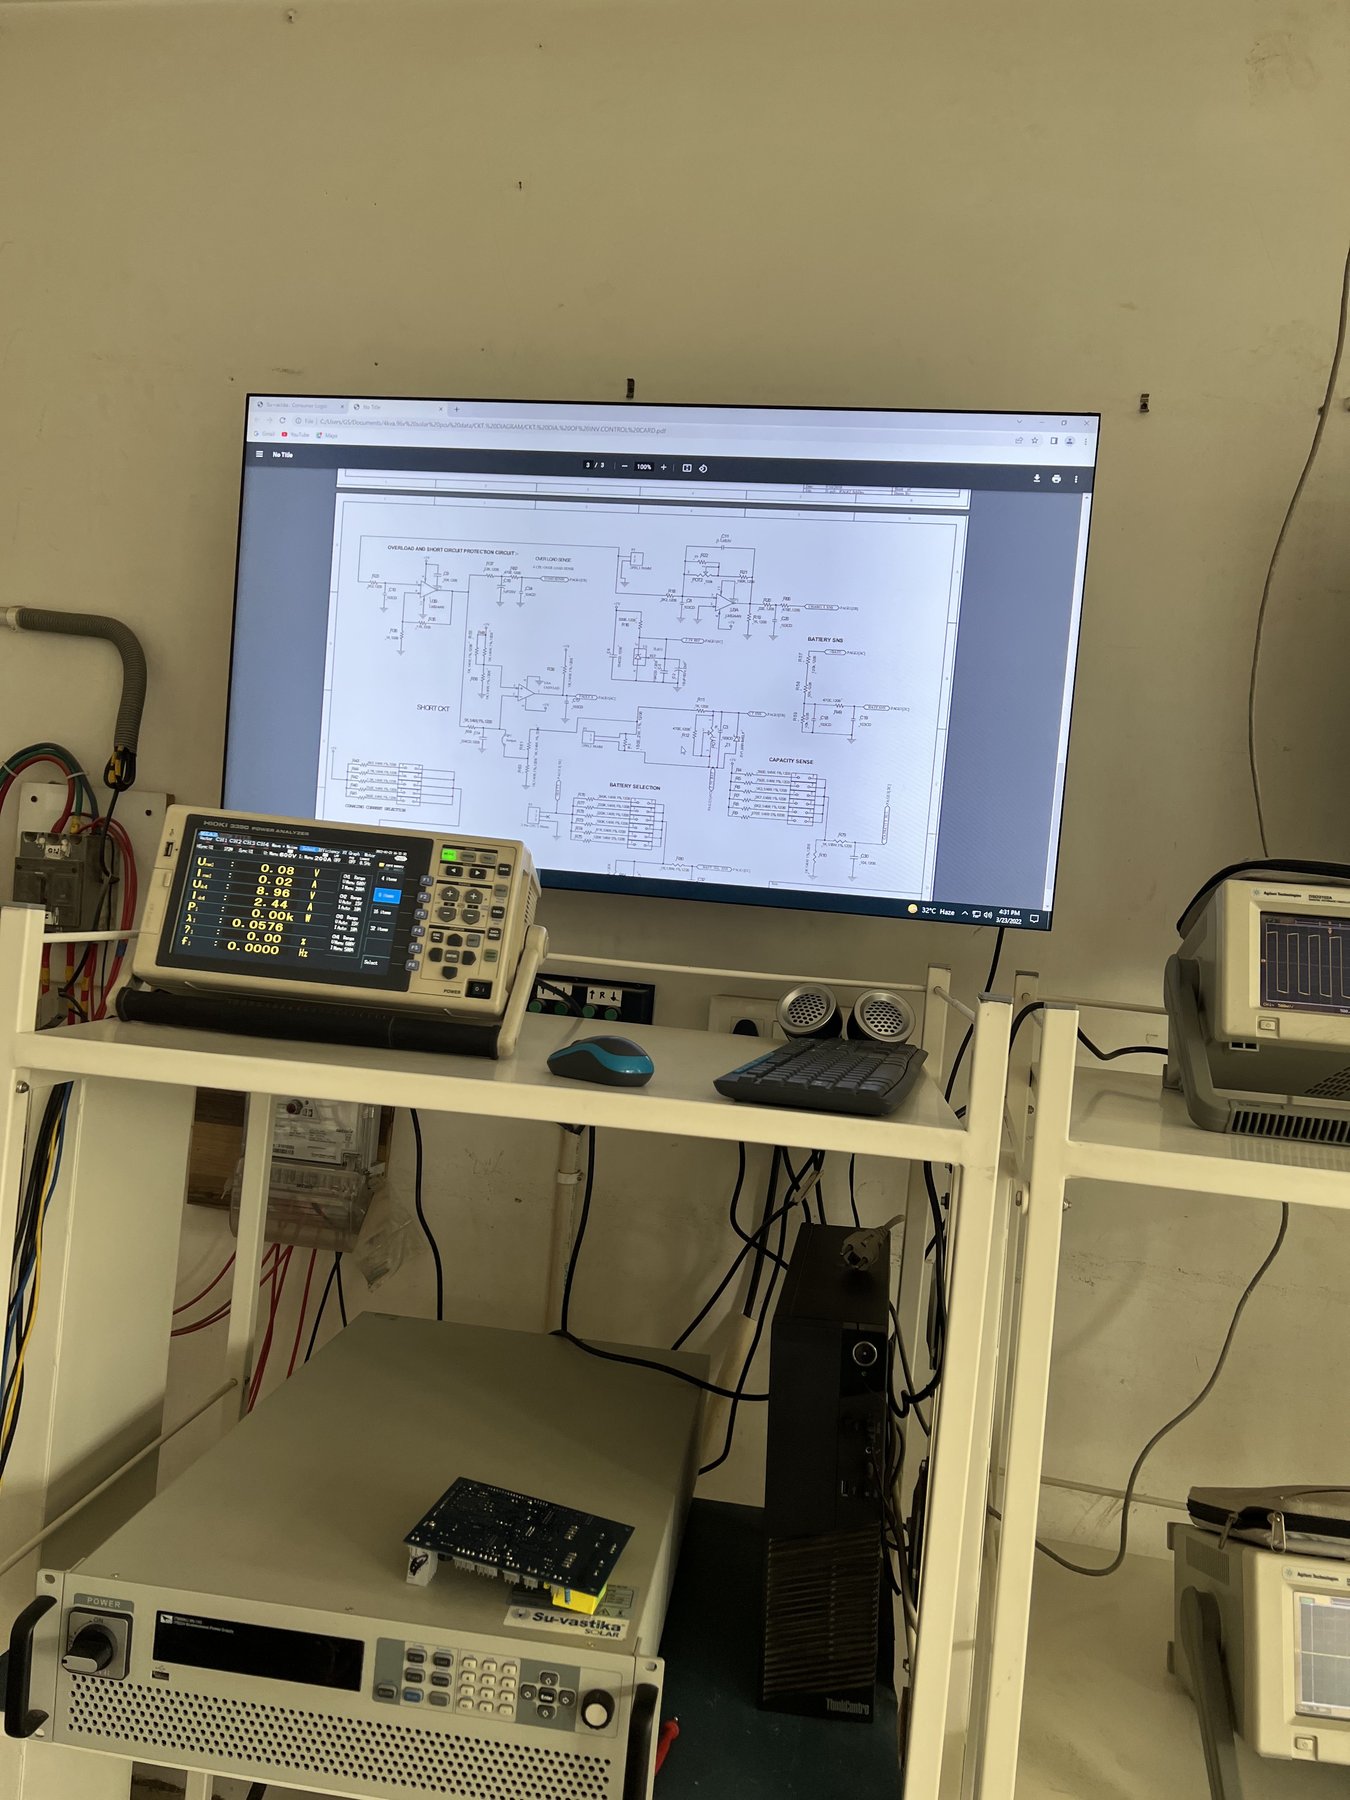
A factory does not live on balance sheets alone. It lives on toolsets, burn-in benches, calibrated test jigs, firmware iterations, vendor credit cycles, and export containers waiting for clearance. Inside the plant, engineers know which MOSFET batch runs hot and which transformer winding handles extreme grid swings.
Then a petition is admitted under the Insolvency and Bankruptcy Code (IBC). A statutory calendar starts ticking. Within weeks, the operational chain freezes, bank accounts are restricted, and the builders who designed the circuitry are informed they have no locus standi. The law assumes a factory can pause like a dormant ledger while financial creditors deliberate. It cannot.
The Manufacturing Mirage is the name of this structural mismatch. India offered two distinct clocks as salvation for its industrial sector: an insolvency framework sold as corporate rescue, and a venture capital model that expects physical factories to scale like mobile applications. Both systems track recovery percentages and valuation multiples on digital dashboards, while the physical plant dies on an entirely different clock.
The Legal Clock and the Dispersal of R&D
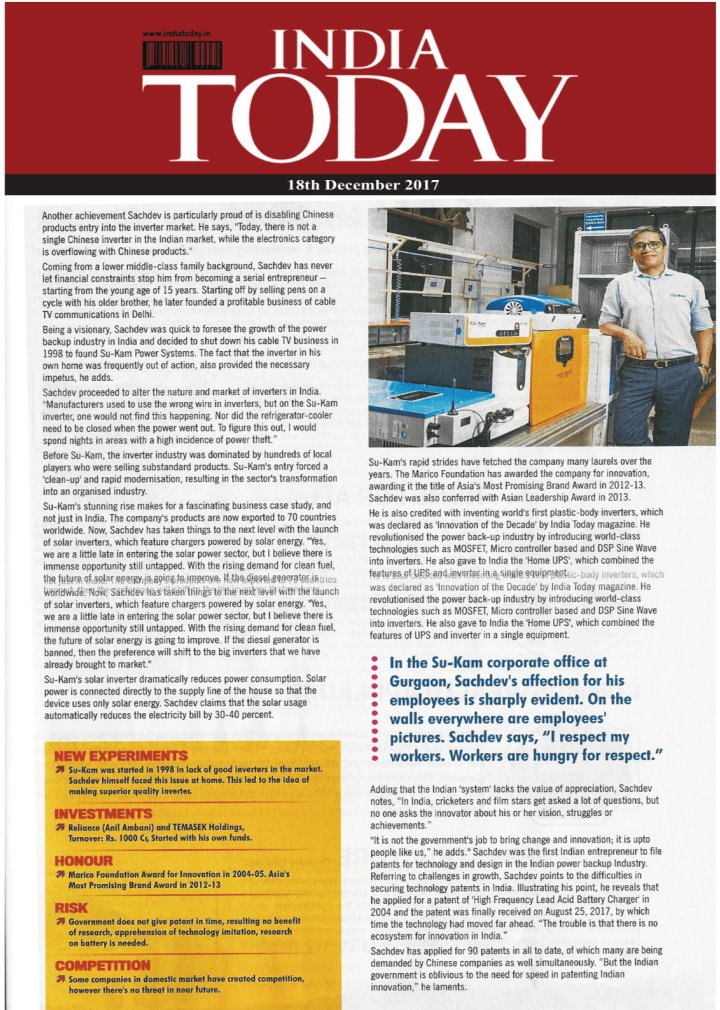
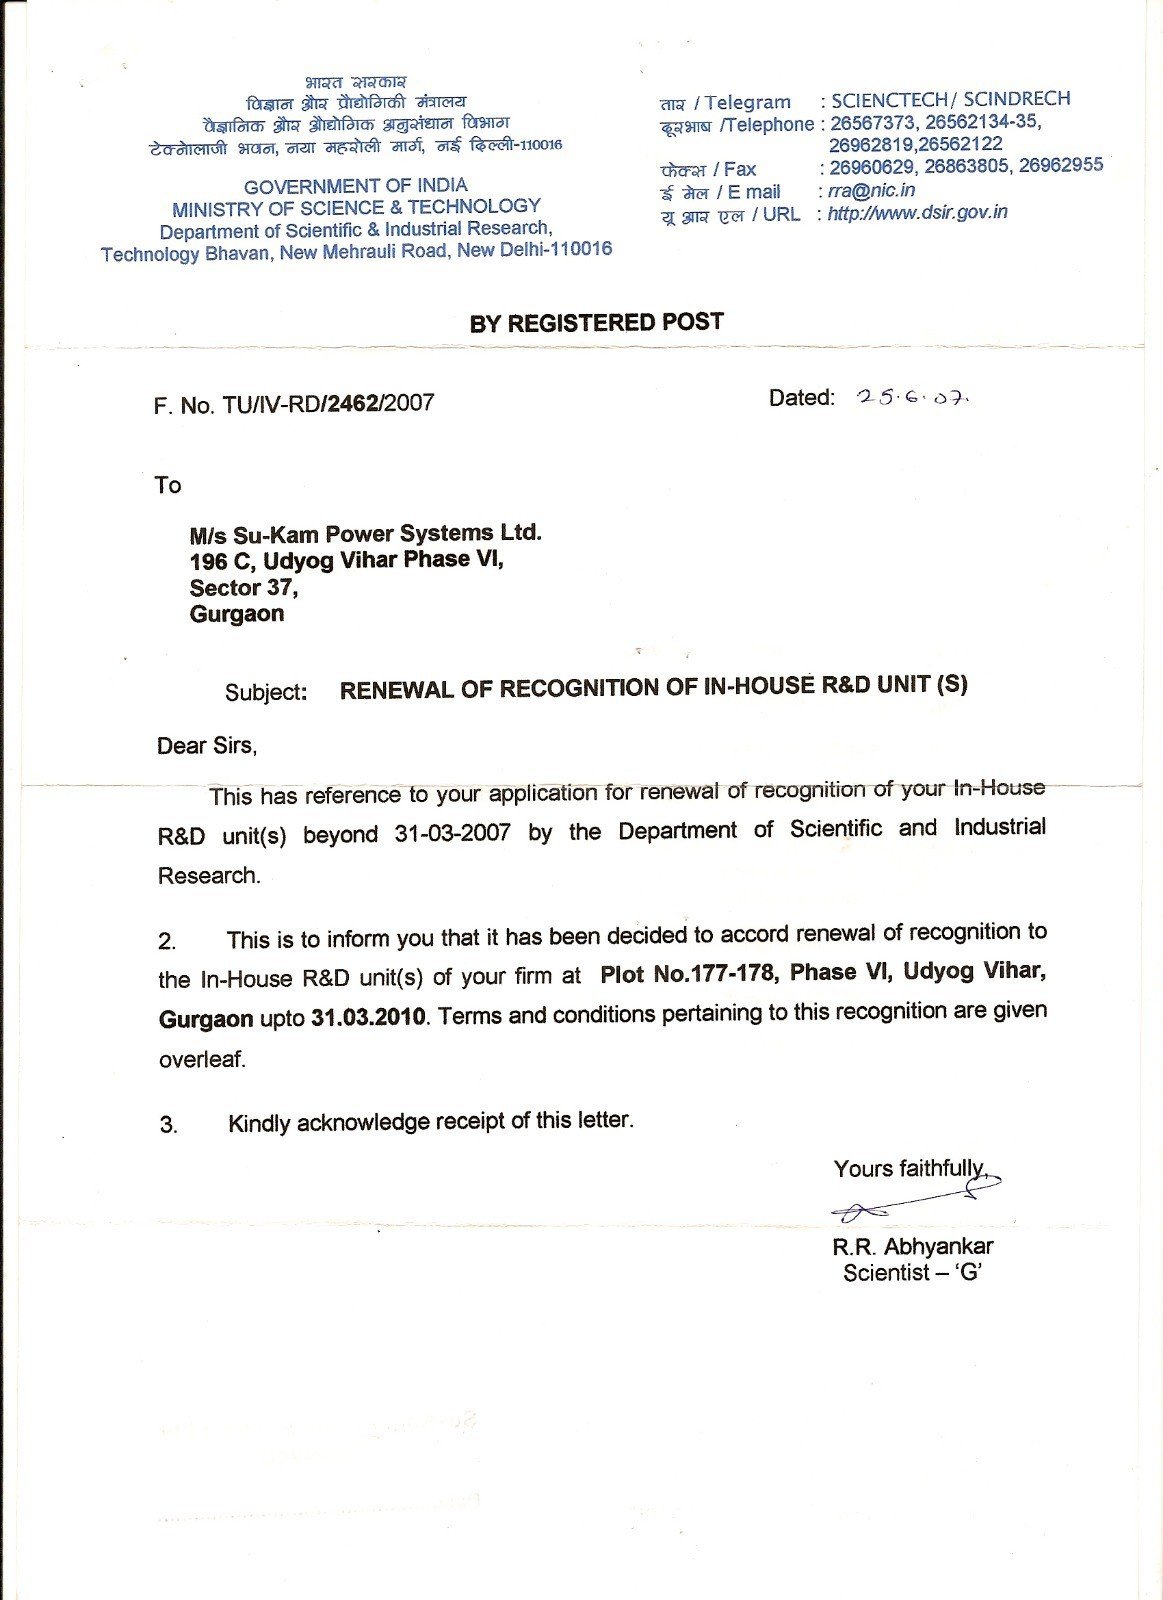
When Corporate Insolvency Resolution Proceedings (CIRP) stall an operating manufacturer, the destruction is rarely recorded in physical scrap. It happens in the market. In the case of Su-Kam Power Systems, 77 domestic and international patents did not vanish from the patent registry — they remained legally recorded. But a living technology programme requires continuous testing, component revisions, and active field warranties. When CIRP scattered the R&D team and halted the lines, the intellectual property was frozen in time.
The economic cost was immediate. While the CIRP accumulated approximately ₹45 crore in procedural expenses and concluded in a pandemic-era asset sale of ₹49.50 crore against roughly ₹8 crore in net lender recovery, the market did not wait. International inverter manufacturers (including Growatt, Sungrow, Solis, Huawei, and Goodwe) grew from a negligible domestic presence in 2018 to capturing the majority of India’s rooftop and commercial solar inverter market by 2024. The institutional machinery focused on auctioning physical sheds, while the domestic manufacturing stack was ceded to foreign supply chains.
Read the shop-floor case study: Part 1 — 77 Patents Dispersed: How CIRP Scattered an Indian Technology Stack
The Venture Clock and the Hardware Trap
The second mirage does not require thirty years of brand equity or an insolvency filing; it begins with venture capital. When software capital entered India’s deep-tech and hardware ecosystem, it imported software expectations — demanding rapid month-on-month growth from physical lines that require eighteen months of tooling, automotive-grade homologation, and thermal stress testing.
The consequences are visible across modern hardware ventures. Ola Electric navigated public listing scrutiny while managing service backlogs and warranty pressures; Log9 entered NCLT proceedings after its domestic LTO cell chemistry bet was outpaced by cheaper, subsidized Chinese LFP imports; Altigreen’s Malur manufacturing plant went quiet under working capital pressure without a formal CIRP being cited. Conversely, Euler Motors represents an instructive contrast — surviving a severe 2023 market contraction not by pursuing hyper-growth software multiples, but by anchoring itself to patient OEM capital from institutional partners like Hero MotoCorp.
Explore the venture hardware analysis: Part 2 — The VC Hardware Graveyard: Software Money in a Physical Plant
The Systemic Machine: Delay, Paper Plans, and Deadlock
This friction is not unique to a single company. Across Indian industrial insolvency, the Code repeatedly manifests three systemic failure patterns:
- Protracted Delay: Videocon Industries was admitted to CIRP on 6 June 2018 and remains locked in consolidated appellate litigation years later.
- The Unimplemented Plan: Educomp Solutions saw an approved resolution plan by Ebix stall indefinitely in appellate proceedings, leaving assets to depreciate.
- Procedural Deadlock: Hero Electric Vehicles (an entity distinct from Hero MotoCorp) saw viable resolution proposals fail to clear the rigid 66% Committee of Creditors (CoC) voting threshold — garnering 47.66% support — forcing an otherwise operational brand into liquidation under Section 33(1)(a).
Against the statutory promise of a 330-day resolution, industrial CIRPs on this site average approximately 744 days. High-profile asset sales like Essar Steel are cited as proof of institutional efficiency, but for operating electronics and automotive manufacturers, prolonged litigation guarantees operational extinction.
Examine the systemic legal record: Part 3 — The IBC Liquidation Machine: Videocon, Educomp, and Hero Electric
The Lock and the Four Reforms
At the centre of this trap sits Section 29A of the IBC. Introduced to prevent willful defaulters from repurchasing their own discounted debt, its rigid disqualification criteria bar honest technical founders — the only individuals possessing the tacit knowledge and supplier relationships necessary to keep custom assembly lines viable. When paired with a Committee of Creditors incentivised solely by short-term recovery rather than long-term industrial output, liquidation becomes the default outcome.
Fixing this institutional failure requires four targeted policy measures:
- Enforce a strictly binding timeline that prevents indefinite litigation extensions during active resolution.
- Mandate operational preservation, ensuring viable assembly lines, testing facilities, and dealer networks remain active under qualified technical management.
- Amend Section 29A to distinguish between genuine commercial distress and willful fraud, allowing ethical builders to submit competitive resolution plans.
- Establish a dual statutory objective, directing resolution professionals and tribunals to balance financial debt recovery with the preservation of domestic manufacturing capability.
The answer to distress is not permanent grievance, but practical reconstruction. Outside the corporate entity resolved under the Code, new ventures like Su-vastika (specialising in heavy-duty lithium energy storage systems) and Kunwwer.ai continue to develop indigenous power electronics, demonstrating that technical capability outlasts legal proceedings.
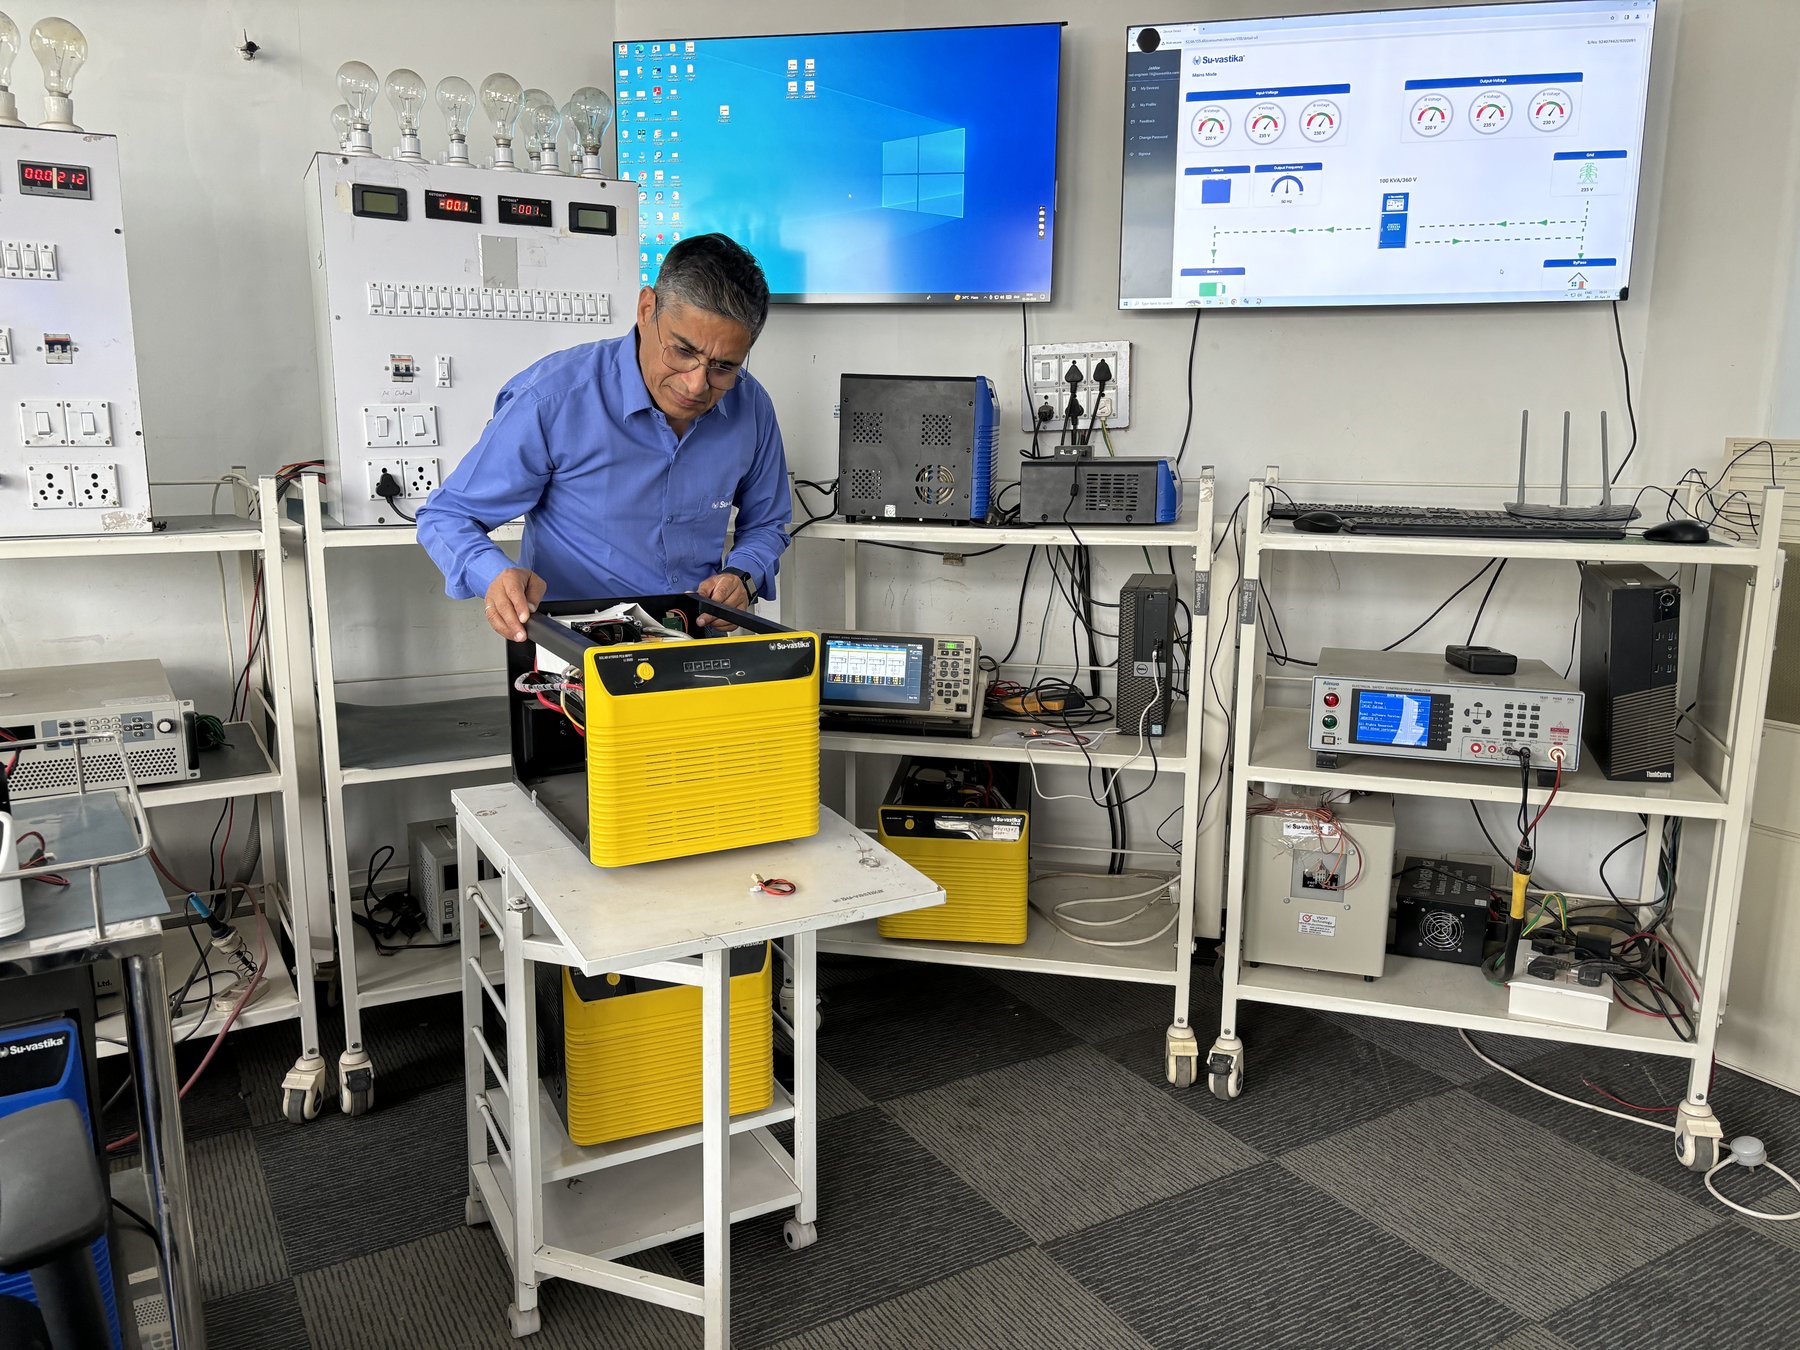
Read the policy blueprint: Part 4 — Section 29A, the Clock, and a Manufacturing Comeback
Navigating the Series
This series is organised by operational and policy focus:
- If you draft legislation or evaluate insolvency policy: Start with Part 4 for the core statutory amendments, and Part 3 for procedural delay and voting deadlock.
- If you build or operate a hardware manufacturing enterprise: Start with Part 1 to understand how IP and supply chains fracture during statutory insolvency, alongside background notes on CIRP mechanics and Section 29A from the older IBC Files series (background companions — separate from Manufacturing Mirage Parts 1–5).
- If you allocate venture or institutional capital to deep tech: Start with Part 2 to examine unit economics, tooling cycles, and the necessity of patient capital in hardware.
The four essays in The Manufacturing Mirage provide an empirical dataset drawn from decades of Indian hardware manufacturing. Start with Part 1 for the shop-floor post-mortem, Part 4 for the reform roadmap. Companion policy instruments live under Manufacturing Policy — separate from this series. For the distribution and brand stack that preceded CIRP, read Building Su-Kam: Sales & Marketing.
Founder, Su-Kam Power Systems (1988–2019) and Kunwwer.ai, and mentor at Su-vastika and several other companies — the “Inverter Man of India” and the “Solar Man of India.” Read his story →
Disclaimer: Kunwer Sachdev exited Su-Kam in 2019 and is not responsible for any activity of the company since. Anyone dealing with Su-Kam does so solely with its current management. Full disclaimer →